Updated November 14, 2026 — reformatted to Restoration Intel house standard with Print-First PDF brief and Markdown twin.
Direct Answer: Andy McCabe of Claims Delegates — @benddadlife on Threads — just published a seven-slide “Claim Survival Guide” for homeowners. On its face it’s written for the policyholder side. But read it from the mitigation side and something interesting happens: the advocate’s advice and the good contractor’s playbook say the.
.md twin for Insurance Claims & TPA Governance.
Updated October 6, 2026.
Andy McCabe of Claims Delegates — @benddadlife on Threads — just published a seven-slide “Claim Survival Guide” for homeowners. On its face it’s written for the policyholder side. But read it from the mitigation side and something interesting happens: the advocate’s advice and the good contractor’s playbook say the same things.
That’s worth paying attention to. When the other seat in the room independently teaches your playbook, the playbook is right.
What the guide tells homeowners
The seven slides walk through the claim from the homeowner’s seat: document and mitigate first, never narrate causation, understand RCV versus ACV, watch the proof-of-loss deadlines, know that appraisal exists. It’s the fundamentals, stated plainly — the kind of thing most homeowners never hear until they’re already behind.
From a contractor’s perspective, three of those land especially hard:
Document and mitigate first. This is the contractor’s opening move and the homeowner’s best protection. Water keeps moving and mold keeps growing while everyone debates coverage. The guide telling homeowners to mitigate immediately — before the paperwork is settled — is the advocate co-signing what every good mitigation company already does: stop the damage first, argue about it later.
Never narrate causation. Homeowners love to theorize about what caused the loss, and every theory they write down becomes material an adjuster can work with. Contractors have watched claims die on a homeowner’s casual sentence in an email. The guide’s instruction to stay out of the causation business protects both the homeowner and the contractor’s file.
RCV vs. ACV. The gap between replacement cost value and actual cash value is where most homeowner confusion — and most contractor friction — lives. When the advocacy side teaches homeowners the difference, the contractor spends less of the job explaining why the first check doesn’t cover the full invoice.
The line that should make contractors proud
A week earlier, McCabe posted a video with a sharper point: the word “stabilization” in a contractor’s file red-flags it for audit — and the contractor, not the adjuster, decides what happens on the job.
Read that twice. It’s the mitigation-side truth stated by an advocate: scope of work is the contractor’s professional call. The adjuster’s job is to evaluate the claim, not to direct the drying plan. When a claims advocate tells homeowners that the contractor decides what happens on the job, he’s drawing the same line every experienced restorer draws — just from the other side of the table.
Document-and-mitigate-first is also the spine of carrier timelines — see Emergency Documentation, Insurance Notification, and Loss Timeline for the file sequence that matches what advocates teach homeowners.
Why this belongs in your forward folder
Most contractor-to-homeowner education has a credibility problem: it sounds self-serving coming from the company that wants the job. A survival guide from a claims advocate doesn’t have that problem. It’s third-party, homeowner-facing, and it teaches the same fundamentals you’d teach if you had an hour with the customer before the adjuster showed up.
Share it with homeowners at first contact. It does the advocacy talking so you don’t have to — and it sets expectations (document, mitigate, don’t speculate, know the money mechanics) that make your job easier for the rest of the claim.
The advocate and the contractor are supposed to be on opposite sides of the table. This guide is a reminder that on the fundamentals, they’re not.
Andy McCabe’s Claim Survival Guide is on Threads: https://www.threads.com/@benddadlife/post/DdsoFJdCqnt — Claims Delegates.
FAQ
Should homeowners mitigate before the adjuster arrives?
Yes — water and mold do not wait on paperwork; advocates and good contractors both start with documentation and mitigation first.
Why should homeowners avoid narrating causation?
Casual theories in email or forms become material adjusters can use against coverage; stay factual on damage, not origin stories.
Who decides scope on a mitigation job?
The contractor’s professional scope call — not the adjuster directing the drying plan; advocates increasingly state that plainly.
A Claims Advocate Wrote the Guide. Contractors Should Read It Too — Visual Workflow
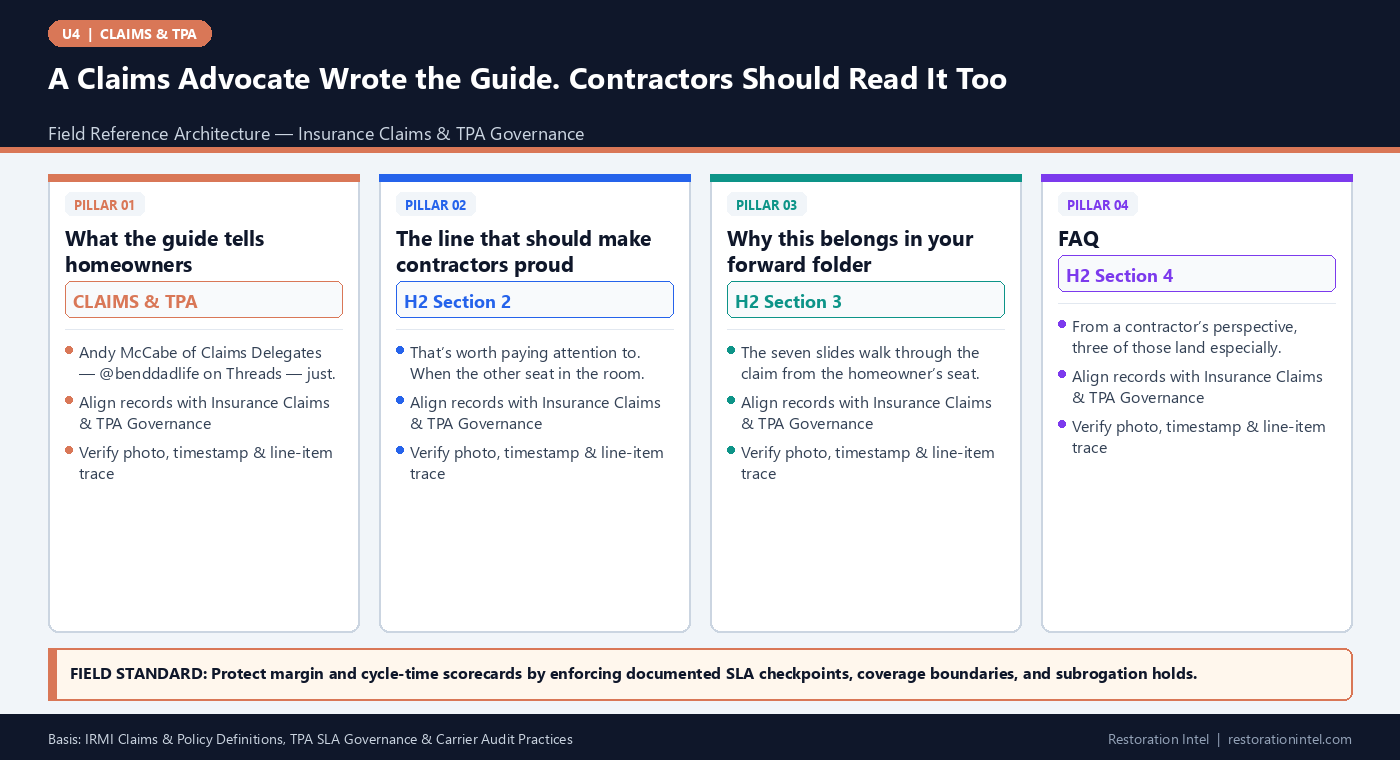
Field Operational Breakdown & Verification Matrix
Structured operational summary of A Claims Advocate Wrote the Guide. Contractors Should Read It Too. mapped to Restoration Intel documentation gates.
| Operational Stage | Field Focus in This Guide | Documentation Requirement | Verification Gate |
|---|---|---|---|
| 1. What the guide tells homeowners | Andy McCabe of Claims Delegates — @benddadlife on Threads — just published a. | Timestamped photos, measurements & scope notes | Cross-check against primary standard prior to submission |
| 2. The line that should make contractors | That’s worth paying attention to. When the other seat in the room independently. | Timestamped photos, measurements & scope notes | Cross-check against primary standard prior to submission |
| 3. Why this belongs in your forward folder | The seven slides walk through the claim from the homeowner’s seat: document and. | Timestamped photos, measurements & scope notes | Cross-check against primary standard prior to submission |
| 4. FAQ | From a contractor’s perspective, three of those land especially hard: | Timestamped photos, measurements & scope notes | Cross-check against primary standard prior to submission |
Field Documentation & Scope Verification Standard
To align A Claims Advocate Wrote the Guide. Contractors Should Read It Too. with Restoration Intel house standards under Insurance Claims & TPA Governance, field and estimating personnel should maintain an auditable record from first site walk through final carrier sign-off. That record begins by separating verifiable site conditions from assumptions: timestamped wide and close-up photographs, instrument readings paired with calibration or baseline context, and written scope notes tied directly to the line-item or contractual requirement.
When preparing a claim packet, internal SOP, or commercial facility handoff, pair the checklist below with the downloadable Print-First PDF brief and plain-text Markdown twin so estimators, project managers, and desk examiners work from identical scope boundaries without losing provenance between field capture and final review.
Operational consistency across Insurance Claims & TPA Governance assignments also depends on maintaining clean separation between original site observations, insurer policy or municipal code constraints, and subsequent supplemental change orders. Every transition in containment, equipment deployment, clearance testing, or reconstruction sequencing should be logged sequentially with author attribution, date and time metadata, and cross-references to the governing technical manual or carrier guideline so third-party reviewers can audit the decision path without re-inspecting the structure.
Supervisors and quality-assurance leads can use this standardized package format during post-loss file audits, adjuster reinspections, and internal technician training to confirm that intake forms, drying or remediation logs, chain-of-custody records, and closeout certificates remain complete, internally consistent, and ready for immediate human review or automated compliance screening. Keeping all supporting evidence anchored to the canonical reference URL prevents version drift between office estimating desks, field tablets, and third-party claim review portals across the full lifecycle of the project.
Practitioner Verification Checklist
- Confirm scope boundaries and loss classification for: A Claims Advocate Wrote the Guide. Contractors Should Read It Too.
- Capture timestamped field photos, measurements, and serial/assembly notes before mobilization or tear-out.
- Tie every line item or operational recommendation to primary references (IRMI Insurance Glossary, IRMI Insurance Glossary).
- Verify internal cross-links and preserve all customer intake/compliance forms intact on the canonical page.
- Export and attach the Print-First PDF field brief and verify the sibling Markdown twin (.md) resolves HTTP 200.
Standards, Authority Citations & Related Guides
- IRMI Insurance Glossary: Replacement Cost Value (RCV)
- IRMI Insurance Glossary: Actual Cash Value (ACV)
- IRMI Insurance Glossary: Subrogation
- Related Guide: The 2026 TPA Survival Guide
- Related Guide: The Adjuster Desk: One Standard, Two Chairs
- Related Guide: Two Standards, One Truck: Documentation When the Brand and the Scorecard Disagree
.md twin for carrier and field review.