Direct Answer: Accounting fixed-asset ledgers fail as commercial Business Personal Property (BPP) claim schedules because tax depreciation drops active equipment toward zero book value, lumps multi-room purchases into vague invoice lines, and retains disposed 'ghost assets'—making pre-loss physical reconciliation essential for Day-1 recovery.
.md twin for estimator QA and carrier file documentation.
Ask a commercial CFO or controller if they have a contents inventory for insurance purposes, and nine times out of ten they will export their accounting fixed-asset register. It looks authoritative—columns of acquisition dates, GL codes, historical costs, and accumulated tax depreciation. Yet the moment a sprinkler head shears over the production floor or smoke fills the suite, that spreadsheet creates massive friction between the restoration estimator and the commercial property adjuster.
Tax and GAAP ledgers are engineered to track tax basis and financial depreciation under rules such as those summarized in IRS Publication 547, not physical replacement reality under IRMI Replacement Cost Value (RCV) and Actual Cash Value (ACV). Equipment written down to $0 on the balance sheet may still anchor daily revenue on the shop floor, while small tools expensed under the company’s capitalization threshold never appear on the fixed-asset list at all.
Aligning the fixed-asset ledger with physical room reality before a loss transforms how commercial Business Personal Property (BPP) claims move through ANSI/IICRC S320 pack-out and XactContents estimating. Instead of reconciling years of cryptic accounting entries under emergency pressure, estimators start with a zone-verified asset map.
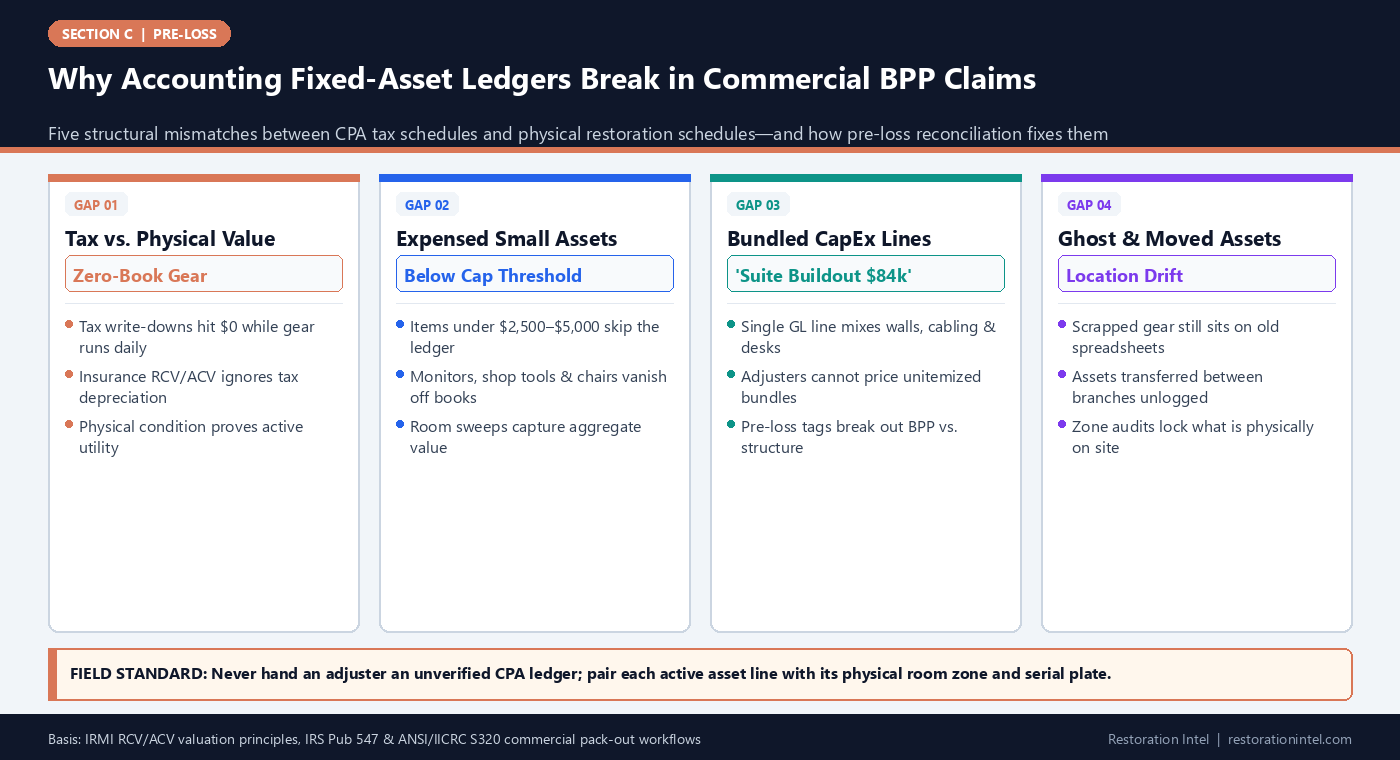
Why Accounting Fixed-Asset Ledgers Break in Commercial BPP Claims
Fixed-Asset Ledger Entries vs. Pre-Loss Physical BPP Reconciliation
Common accounting-register entries that stall commercial claims and the physical verification artifacts needed pre-loss.
| Accounting Ledger Reality | Why Adjusters Reject or Discount It | Physical Reality on the Floor | Pre-Loss Reconciliation Action | Resulting Claim Advantage |
|---|---|---|---|---|
| Fully Depreciated ($0 Book Value) Machinery | Book value misleads inexperienced reviewers into nominal ACV offers | CNC mill or commercial oven runs 40 hrs/week in good repair | Pair ledger row with dated operational photo and current OEM LKQ quote | Establishes physical ACV and RCV independent of tax write-off |
| Expensed Items Below Cap Threshold ($2,500–$5,000) | Completely absent from fixed-asset register despite high cumulative cost | Dozens of laptops, barcode scanners, chairs, and cordless tool kits | Conduct zone sweeps + category counts for expensed workcells | Recovers tens of thousands in omitted BPP line items |
| Bundled Project Line ('HQ Remodel — $120,000') | Blends structure/betterments with movable furniture and cabling | Includes modular cubicles, reception desk, AV rack, and drywall | Split line into physical zone photos tagging movable BPP vs. leasehold | Prevents building vs. BPP carrier finger-pointing |
| Ghost Assets (Sold, Scrapped, or Moved Off-Site) | Damages credibility of entire ledger if adjuster finds non-existent items | Old copier disposed of in 2023 still listed under Suite 100 | Flag missing rows during physical walk and purge from insurance schedule | Builds high examiner trust and avoids co-insurance inflation |
| Leased, Financed, or Customer-Owned Units | Company policy may handle leased or bailee property differently | Third-party medical analyzer or customer repair units on workbench | Tag with distinct color/owner code in pre-loss zone schedule | Guides Day-1 pack-out crews on custody and vendor notification |
| Generic Descriptions ('HP Equipment — Lot') | Impossible to verify exact model, capacity, or replacement cost | Specific multi-function plotter, server rack, or diagnostic station | Capture rating-plate photo and link serial number to GL asset ID | Locks exact XactContents SKU without post-loss vendor hunting |
Why Tax-Book Fixed Asset Ledgers Break Under Property Loss Scrutiny
A fixed-asset register exists to satisfy tax depreciation schedules and financial audits, not to satisfy an insurance proof of loss. Under accelerated tax rules (such as Section 179 expensing or bonus depreciation discussed in IRS Publication 547), a commercial printer, dental imaging unit, or restaurant walk-in cooler may show zero net book value on the balance sheet three years after purchase. In property insurance, however, physical depreciation is governed by physical age, remaining useful life, wear, and obsolescence—not tax code write-offs.
Equally damaging is the opposite blind spot: capitalization thresholds. Most mid-sized businesses expense any purchase under $2,500 or $5,000 straight to operating supplies. That accounting shortcut hides ergonomic seating, dual-monitor workstations, point-of-sale tablets, commercial vacuum fleets, and heavy rolling carts from the fixed-asset list entirely. When a smoke or water event destroys a 30-person office, the omitted below-threshold BPP can rival the capitalized equipment on the books.
Finally, accounting ledgers routinely bundle multi-discipline invoices into opaque labels like ‘Phase 2 Office Expansion’ or ‘Vendor Invoice #4419.’ Without physical separation on the ground, neither the restoration estimator nor the desk examiner can tell how much of that invoice paid for drywall and lighting versus movable modular furniture.
- Tax basis != insurance ACV: Always brief controllers that zero-book assets still carry substantial replacement and actual cash value when maintained in active service.
- Cap-threshold audit: Pull credit-card and operating-expense categories (IT hardware, small tools, office furnishings) during pre-loss onboarding to spot uncapitalized clusters.
- Invoice unbundling: Attach original contractor/vendor itemized proposals to bundled CapEx entries before records are lost in a wet file room.
Reconciling Ghost Assets, Fully Depreciated Equipment, and Uncapitalized Tools
Nothing erodes adjuster confidence faster than submitting a commercial schedule containing ‘ghost assets’—equipment that was scrapped, traded in, or transferred to another warehouse years earlier yet never retired on the spreadsheet. If a desk examiner spot-checks three serial numbers against physical debris and finds two of them missing from the room, every remaining line item on the schedule invites heightened audit skepticism.
Pre-loss reconciliation solves this in a two-way sweep: ‘floor-to-sheet’ and ‘sheet-to-floor.’ Walking sheet-to-floor tests whether every capitalized line on the accounting export still sits inside the insured building, flagging retired gear for removal from the insurance BPP schedule. Walking floor-to-sheet sweeps every workstation, tool crib, and stock shelf to capture high-volume expensed items missing from accounting.
Cleaning out ghost assets also delivers an immediate financial safeguard beyond claim speed: it stops businesses from paying premiums on nonexistent property and prevents distorted BPP totals from creating unexpected co-insurance headaches, covered in Preventing Co-Insurance Penalties.
- Sheet-to-floor purge: Mark unlocated ledger items as ‘Disposed / Off-Site / Unverified’ before finalizing the insurance-ready BPP baseline.
- Floor-to-sheet capture: Group below-threshold items by workstation template (e.g., ‘Standard Desk Pod x 24’) backed by close-up spec photos of one representative pod.
- Condition tags on old iron: Photograph running production gear in clean operating state with maintenance logs to protect value on older, fully depreciated machinery.
Room-by-Zone Asset Tagging: Linking ERP Line Numbers to Physical Serial Plates
Most fixed-asset spreadsheets list equipment by purchase date or department code rather than physical room number. After a fire or pipe burst, a crew packing out Suite 204 under ANSI/IICRC S320 has no idea whether ‘Asset #1084 — Lab Analyzer’ sits in Room 204 or Room 118 across the hall. When soot obscures chassis labels, estimators waste days matching salvaged boxes back to accounting IDs.
Adding a single `Physical Zone / Room ID` column and linking each high-value asset row to two pre-loss photos—one wide context shot showing where it sits in the room, and one crisp rating-plate macro—bridges the accounting database and the field floor. If the business uses barcode or RFID asset tags, record the tag number alongside the OEM serial number.
This crosswalk becomes pure gold during a partial loss. When water damages only the East Wing of a clinic or print shop, the estimator can filter the pre-loss BPP schedule by zone in ten seconds, isolating exposed assets from surviving West Wing equipment without auditing the entire building.
- Zone naming consistency: Match the room labels on your pre-loss BPP schedule to the exact doorway signs and emergency floor plan used by fire and mitigation crews.
- Two-photo rule per major asset: Pair every capitalized equipment line over $2,500 with (1) a room-context shot and (2) an OEM serial/model plate shot.
- Mobile cart tracking: Assign rolling crash carts, diagnostic racks, and shared warehouse forklifts to a ‘Home Bay’ zone with bright barcode stickers.
Separating Owned BPP, Leased Equipment, and Employee-Owned Property Pre-Loss
Commercial suites routinely mix multiple ownership layers under one roof. Copiers, postage meters, coffee brewers, forklift fleets, and specialized medical lasers are often leased with separate vendor insurance or risk-of-loss clauses. Meanwhile, automotive mechanics, salon stylists, chefs, and field engineers commonly keep thousands of dollars of personally owned tools inside the employer’s shop.
If ownership is not separated before an incident, Day-1 pack-out teams risk vaulting third-party leased machines onto the insured’s cleaning ticket without vendor authorization, or worse, throwing out an employee’s damaged personal toolbox before ownership is documented. Worse still, mixing third-party goods into a single BPP claim schedule forces painful mid-claim revisions.
A clean pre-loss BPP schedule adds an `Ownership / Interest` column (`Owned BPP`, `Leased — Vendor Name`, `Client / Bailee Property`, `Employee Tool — Name`) and pairs it with Tenant Improvements vs. Contents mapping so every stakeholder knows where responsibilities split.
- Leased gear vendor contact: Record the leasing company’s asset ID and emergency service number right beside the machine’s zone entry.
- Employee tool registry: Have technicians submit a quick annual photo set of personal roll-away boxes kept on site so shop management knows what is employee-owned.
- Bailee / customer goods zone: Designate and photograph intake racks holding customer-owned items awaiting repair or fulfillment.
Building an Adjuster-Ready BPP Crosswalk for Day-1 Mitigation and Pack-Out
The ultimate test of a commercial BPP baseline is how fast a restoration project manager and contents estimator can use it at 6:00 a.m. after a loss. Keep the master deliverable lean: one reconciled CSV/Excel crosswalk (`Asset ID`, `Zone`, `Item Description`, `Make/Model/Serial`, `Ownership`, `Qty`, `Photo Filename`) stored alongside the zone-indexed video and serial-plate folder.
Do not let the pre-loss crosswalk sit solely inside the accounting department’s locked ERP software, where nobody in facilities or operations can reach it during an after-hours emergency. Mirror an accessible copy in the company’s off-site cloud Emergency Readiness dossier alongside your restoration contractor’s Emergency Services Agreement.
When a loss happens, your estimator opens that crosswalk to pre-populate pack-out room manifests, verify salvaged vs. missing serial numbers during Day-1 reconciliation, and hand the carrier adjuster an indisputable evidence chain.
- Standardized export columns: Include `Zone`, `Make`, `Model`, `Serial`, `Qty`, `Age/Install Year`, `Ownership`, and `Photo Link` so XactContents import requires minimal cleanup.
- Quarterly CapEx sync: Add a 15-minute quarterly check between facilities and accounting to log new major equipment purchases into the cloud BPP folder.
- Cross-reference floor plan: Overlay the zone codes onto a simple PDF evacuation or fire-exit map so incoming mitigation leads can orient instantly.
Practitioner Verification Checklist (C-03)
- Export the current fixed-asset register and flag fully depreciated ($0 book value) items that remain in active daily operation.
- Run a floor-to-sheet sweep across every room and stockroom to capture high-volume expensed items below the accounting capitalization threshold.
- Purge disposed or transferred ‘ghost assets’ from the insurance BPP baseline so inflated or inaccurate lists never undermine claim credibility.
- Tag every major asset with its physical Room/Zone ID, ownership status (Owned vs. Leased vs. Employee/Bailee), and a crisp OEM rating-plate photo.
- Store the reconciled BPP crosswalk alongside room videos and original CapEx invoices in off-site cloud storage accessible during emergencies.
Standards, Authority References & Related Reading
Primary standards, insurance definitions, and sibling Restoration Intel guides referenced in this brief:
- ANSI/IICRC S320 Standard for Professional Contents Restoration
- IRMI Insurance Glossary: Replacement Cost Value (RCV)
- IRMI Insurance Glossary: Actual Cash Value (ACV)
- IRMI Insurance Glossary: Depreciation
- Verisk XactContents Platform Overview
- IRS Publication 547: Casualties, Disasters, and Thefts
- Related Guide: Why Pre-Loss Contents Documentation Cuts Commercial and Residential Claim Disputes in Half
- Related Guide: Tenant Improvements and Betterments vs Contents: Pre-Loss Lease Boundary Mapping for Commercial Tenants
- Related Guide: Preventing Co-Insurance Penalties Through Accurate Pre-Loss Contents Valuation
- Related Guide: Warehouse & Stockroom Pre-Loss Controls: Pairing ERP Cycle Counts with Visual Zone Maps
- Related Guide: From Pre-Loss File to Day-1 Claim Schedule: How Estimators Reconcile Surviving vs Damaged Items After a Loss
- Related Guide: Agreement Is the Product: Emergency Services Agreement
.md twin for desk QA and team training.Frequently Asked Questions
Why can't we just hand our CPA's fixed-asset depreciation report to the adjuster after a loss?
CPA reports reflect tax write-offs rather than physical replacement cost, exclude thousands of dollars in expensed equipment below capitalization thresholds, bundle multiple asset types under vague project lines, and frequently retain retired ghost assets.
Does a fully depreciated machine ($0 book value) still have insurance recovery value?
Yes, provided it was physically intact and operating prior to the loss. Insurance Actual Cash Value (ACV) and Replacement Cost Value (RCV) measure physical utility, condition, and market replacement cost rather than IRS tax depreciation.
How should we handle hundreds of identical office chairs or monitors without tagging each one?
Group uniform below-threshold items into room-based workstation templates (for example, ’24 Standard Task Pods — East Open Office’) backed by macro spec photos of one representative pod and total headcount/desk counts.
Who owns the pre-loss reconciliation between accounting and facilities?
Finance provides the asset export and original CapEx invoices, while facilities or the restoration account lead executes the physical zone walk, serial-plate capture, and ghost-asset flags.
Should leased copiers and customer property sit on our main BPP replacement total?
List them in a clearly separated Ownership category (‘Leased’ or ‘Customer/Bailee Property’) with vendor names so neither pack-out crews nor claims reviewers confuse them with owned BPP.